Quick Answer
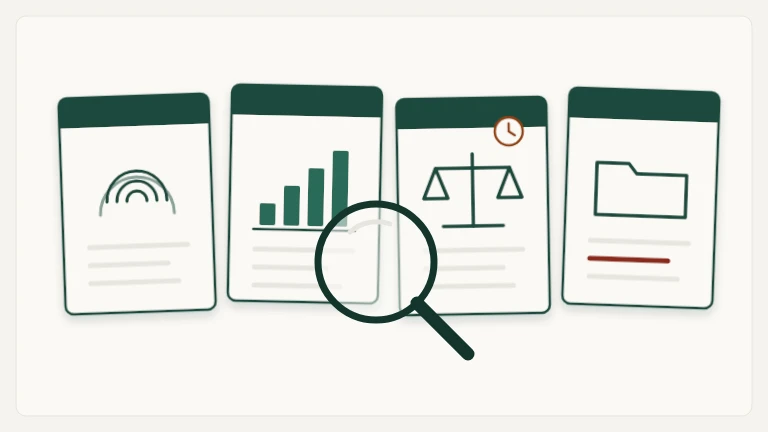
A screening report is not one verdict. It is four separate records, each answering a narrow question: an identity trace, a credit file, court records, and a criminal search. Under 15 U.S.C. § 1681c(a), most negative credit and court entries may not be reported once they are more than seven years old, bankruptcy runs ten years, and convictions have no federal cap. If the report leads you to deny an application, § 1681m(a) has you tell the applicant. Statute text last checked October 2, 2026.
Key Takeaways
- Read each section for its own question. The identity trace confirms who the applicant is, the credit file shows debt history, court records show lawsuits, and the criminal search shows convictions and arrests.
- Lookback periods differ by section. Most negative credit items run seven years, bankruptcy ten, and court records seven years from entry or until the limitations period ends, whichever is longer (§ 1681c(a)).
- A credit file usually does not show rent. Rent appears only when a prior landlord or rent bureau reported it.
- Check the disposition on every court entry. A filing that was dismissed can still appear as a suit, so read what happened to it.
- HUD’s 2016 criminal-records guidance has been rescinded. The Fair Housing Act and your state and local laws still apply to how you use criminal history.
- A denial based on the report triggers a notice. Section 1681m(a) lists what the notice must say.
The Four Sections at a Glance
The report you receive is assembled from different sources. The screening company pulls a credit file from a nationwide credit bureau, searches court dockets for lawsuits, and queries criminal records. The CFPB lists the possible contents as credit reports, rental history with eviction actions and lawsuits, employment verification, criminal history, sex offender registries, and a risk score or recommendation based on criteria you select. Each source has its own rules on how far back it may reach.
1. The Identity Trace
The first section checks that the applicant’s name, Social Security number, and date of birth line up across records. It also lists past addresses and other names the person has used.
What it shows:
- Address history. Where bills and applications were mailed in the past.
- Name variations. Maiden names, legal changes, and spelling differences.
- A match or a mismatch. Whether the identifiers you supplied agree with the records.
What it does not show:
- Where your applicant actually lived. A credit header records a mailing address, not occupancy.
- Whether the identity is theirs. A match shows the identifiers agree, not who submitted the application.
A consumer reporting agency must follow reasonable procedures to assure maximum possible accuracy (15 U.S.C. § 1681e(b)). A mismatch is a reason to ask your applicant for identification and clarification, not a verdict.
2. The Credit File
The credit file lists accounts (tradelines), inquiries, collections, and public-record items such as bankruptcy. Section 1681c(a) sets how long adverse items may appear:
- Bankruptcy: ten years from the date of the order for relief (§ 1681c(a)(1)).
- Paid tax liens: seven years from the date of payment (§ 1681c(a)(3)).
- Collections and charge-offs: seven years (§ 1681c(a)(4)). Under § 1681c(c), that period starts 180 days after the delinquency that led to the collection or charge-off began.
- Other adverse items: seven years, other than records of convictions (§ 1681c(a)(5)).
The exceptions in § 1681c(b) cover credit transactions of $150,000 or more, life insurance underwriting of $150,000 or more, and employment at $75,000 or more. None of them describes an ordinary rental application.
What it does not show:
- Rent history. Monthly rent usually does not appear on a credit file unless a prior landlord or rent bureau reported it. An applicant with a thin credit file may have paid rent on time for years.
- Civil judgments. The nationwide credit bureaus stopped including civil judgments and tax liens in credit files beginning July 1, 2017, under the National Consumer Assistance Plan. Lawsuits now reach you through a court-records search, covered next.
3. Court Records
This section comes from a docket search. It is where you see eviction filings and money judgments from earlier tenancies.
What it shows:
- Eviction filings and judgments. The case, the court, the filing date, and the outcome.
- Money judgments. Amounts a court ordered a tenant to pay.
How long it may appear. Section 1681c(a)(2) allows civil suits and civil judgments for seven years from the date of entry, or until the governing statute of limitations has expired, whichever is longer.
What it does not show:
- Informal move-outs. If a tenant left after a notice and you never filed, no court record exists.
- The full story of a dismissed case. A dismissed or withdrawn filing can still appear as a suit. Read the disposition line, and treat a dismissal differently from a judgment for the landlord.
If an entry looks wrong, your applicant can dispute it with the screening company. A report may list one case several times, once for each stage, so match the case numbers before you count a single case as several.
4. The Criminal Search
The criminal search draws on county and state records and on sex offender registries.
What it shows:
- Convictions. Section 1681c(a)(5) excludes records of convictions from the seven-year rule, so federal law sets no reporting cap for them.
- Arrest records. Under § 1681c(a)(2), records of arrest follow the seven-year rule.
What changed in 2025. HUD rescinded its 2016 Office of General Counsel guidance on criminal records under the Fair Housing Act in November 2025, together with a 2015 notice on arrest records and a 2022 implementing memo. Rescinding guidance does not repeal the Fair Housing Act, and state and local laws on arrests, conviction history, and individualized review still apply. Some states set their own reporting limits. California’s Civ. Code § 1786.18(a), for example, uses seven years from disposition, release, or parole for the reports it covers.
What it does not show:
- What the conduct was. An arrest is a record that police acted, not a finding about what happened.
- Sealed or expunged records in your state. Confirm what your state allows the report to include.
Because rules on criminal history differ by state and city, set your criteria in writing before you read any report, and check the law where your property sits. For Texas, see the Texas criminal background guide.
5. The Score or Recommendation
Many reports end with a score or a pass, review, or decline label. That label is the screening company applying criteria, either its own or ones you selected, to the sections above. It does not add a fifth source of facts. The decision remains yours, so read the sections the label rests on.
How to Use the Report in Your Decision
- Write your criteria first. Set income, credit, and rental-history standards before you open any report, and apply them to every applicant.
- Check the dates. Compare each negative entry with the lookback periods above.
- Verify independently. Ask for pay stubs, bank statements, or a prior landlord reference rather than relying only on the summary.
- Send the notice if you deny or take another adverse action based on the report. Section 1681m(a) has you give notice orally, in writing, or electronically that includes the name, address, and phone number of the consumer reporting agency, a statement that the agency did not make the decision, and the applicant’s rights to a free copy within 60 days (§ 1681j(b)) and to dispute accuracy. For California, see the adverse action guide. For Texas, see the denial notice guide.
- Keep a record of what you relied on. See defensible decision records.
Questions Owners Ask
Does a credit score tell me whether my applicant pays rent? Not by itself. A score reflects debt accounts, and rent appears only when someone reported it.
Can I rely on a dismissed eviction filing? Read the disposition first. A dismissal and a judgment for the landlord tell you different things.
How old is too old? For most negative credit and court entries, federal law sets seven years, with bankruptcy at ten. Convictions have no federal limit, and your state may set one.
What This Guide Does Not Cover
This guide covers the sections of a consumer report used to screen rental applicants under the federal Fair Credit Reporting Act, as of the check date above. It does not predict how a court will rule on your facts.
It does not cover:
- Employment screening.
- State and local criminal-history and fair-chance laws in detail.
- Admission rules for subsidized housing.
- How to choose a screening company.